


Egyptian Exchange Evening Session - 24 September 2026

Egyptian Exchange Evening Session - 24 September 2026
Introduction: Reading the Closing Transactions
The Egyptian Exchange closed Thursday’s session on a negative note, with the EGX30 index falling 0.83% to close at 54,200 points, while the EGX70 declined 1.92% to 2,150 points. Local and international news flow shaped the overall market context, warranting an expanded analytical read to understand session dynamics and potential implications for upcoming sessions.
Locally, the pivotal decision on interest rates remains keenly awaited by investors, especially after Norway’s central bank raised rates to 4.50% and signaled further hikes, alongside the Institute of International Finance’s forecast that Egypt’s government debt will reach 79.7% of GDP in Q2 2026. Session liquidity stood at EGP 4.2 billion, spread across 110 traded stocks, with banking sector shares accounting for 10.88% of total turnover, led by Commercial International Bank (CIB) as the most active.
Globally, the yield on the 30‑year US Treasury continued its record climb to 5.44%, the highest level since 2004, while crude oil prices breached the $103 per barrel mark amid ongoing geopolitical tensions between Washington and Tehran. Meanwhile, Sweden and Switzerland held their policy rates steady, and Fitch indicators suggested that any potential US sanctions on the UAE branches of Banque Misr would have only a limited impact on the bank’s credit rating.
Technical Analysis of the Main Indices
EGX30 Index

The EGX30 chart shows price action confined to a tight range between an immediate resistance ceiling at 54,500 points and a primary support zone at 53,800 points. Technical reading indicates the formation of a new higher low near the 53,950‑point area, while the medium‑term downtrend remains intact unless the index decisively breaks above the 54,700‑point resistance.
EGX70 Index

The EGX70 faced mounting selling pressure met with limited buying interest in small‑ and mid‑cap stocks, closing the session at 2,150 points, down 1.92%. Technical indicators show a break of support at the 2,200‑point level, with psychological and geometric support around 2,100 points, and the overall bias remains bearish unless the index records a genuine upside break above the 2,250‑point hurdle.
#### Key Support and Resistance Levels (Comparison Table)
| Index | Closing Price | Change % | Primary Support | Primary Resistance | Secondary Support | Secondary Resistance |
|---|---|---|---|---|---|---|
| EGX30 | 54,200 | -0.83% | 53,800 | 54,700 | 53,300 | 55,200 |
| EGX70 | 2,150 | -1.92% | 2,100 | 2,250 | 2,050 | 2,300 |
#### Liquidity Ratios and Activity Distribution
| Sector | Liquidity Share | Active Stocks | Traded Value (EGP m) |
|---|---|---|---|
| Banks & Financial Services | 10.88% | 23 | 450 |
| Real Estate & Construction | 7.62% | 18 | 320 |
| Industry | 5.41% | 15 | 210 |
| Consumer Goods | 4.23% | 12 | 180 |
| Energy & Petroleum Services | 3.15% | 8 | 130 |
| Other Sectors | 58.71% | 34 | 2,450 |
| Total | 100% | 110 | 3,740 |
Main Sector Performance
1: Banks & Financial Services
Banking stocks captured the bulk of today’s liquidity as investors awaited the interest‑rate decision. Commercial International Bank (CIB) edged higher despite global tightening concerns, posting a modest gain bolstered by strong capital buffers. Conversely, the dollar’s advance versus the Egyptian pound pressured bank net interest margins, while foreign liquidity remains in search of hedging opportunities across asset classes.
2: Real Estate & Construction
The real‑estate sector faced selling pressure due to rising construction costs and drying Arab liquidity, with the sub‑index slipping 0.45% today. Reports indicate that Al‑Qalaa Holdings turned profitable, generating EGP 94.7 billion in revenue during H1 2026, whereas Talaat Moustafa Group (TMGH) continued to post successive declines amid expectations of higher financing costs.
3: Industry
The industrial sector showed average activity, with investors focusing on energy‑ and raw‑material‑linked stocks; the decline was limited to 0.28%, supported by non‑oil export growth data pointing to a gradual improvement in external performance.
4: Energy & Petroleum Services
Geopolitical tensions in the Middle East underpinned global oil prices, which positively impacted sector shares, with several names gaining 2‑3% today as investors focused on export‑oriented and exploration firms.
Core Stock Analysis
Commercial International Bank (COMI) Stock

COMI outperformed the broader market today, rising 1.2% to close at EGP 154.50, buoyed by high liquidity that exceeded EGP 450 million. Technical charts reveal a — pattern with a price target of EGP 160, while the crucial support remains around EGP 150. Expectations of stable net interest margins, given the Egyptian central bank’s steady policy rate, underpin the domestic banking‑asset performance.
Talaat Moustafa Group (TMGH) Stock
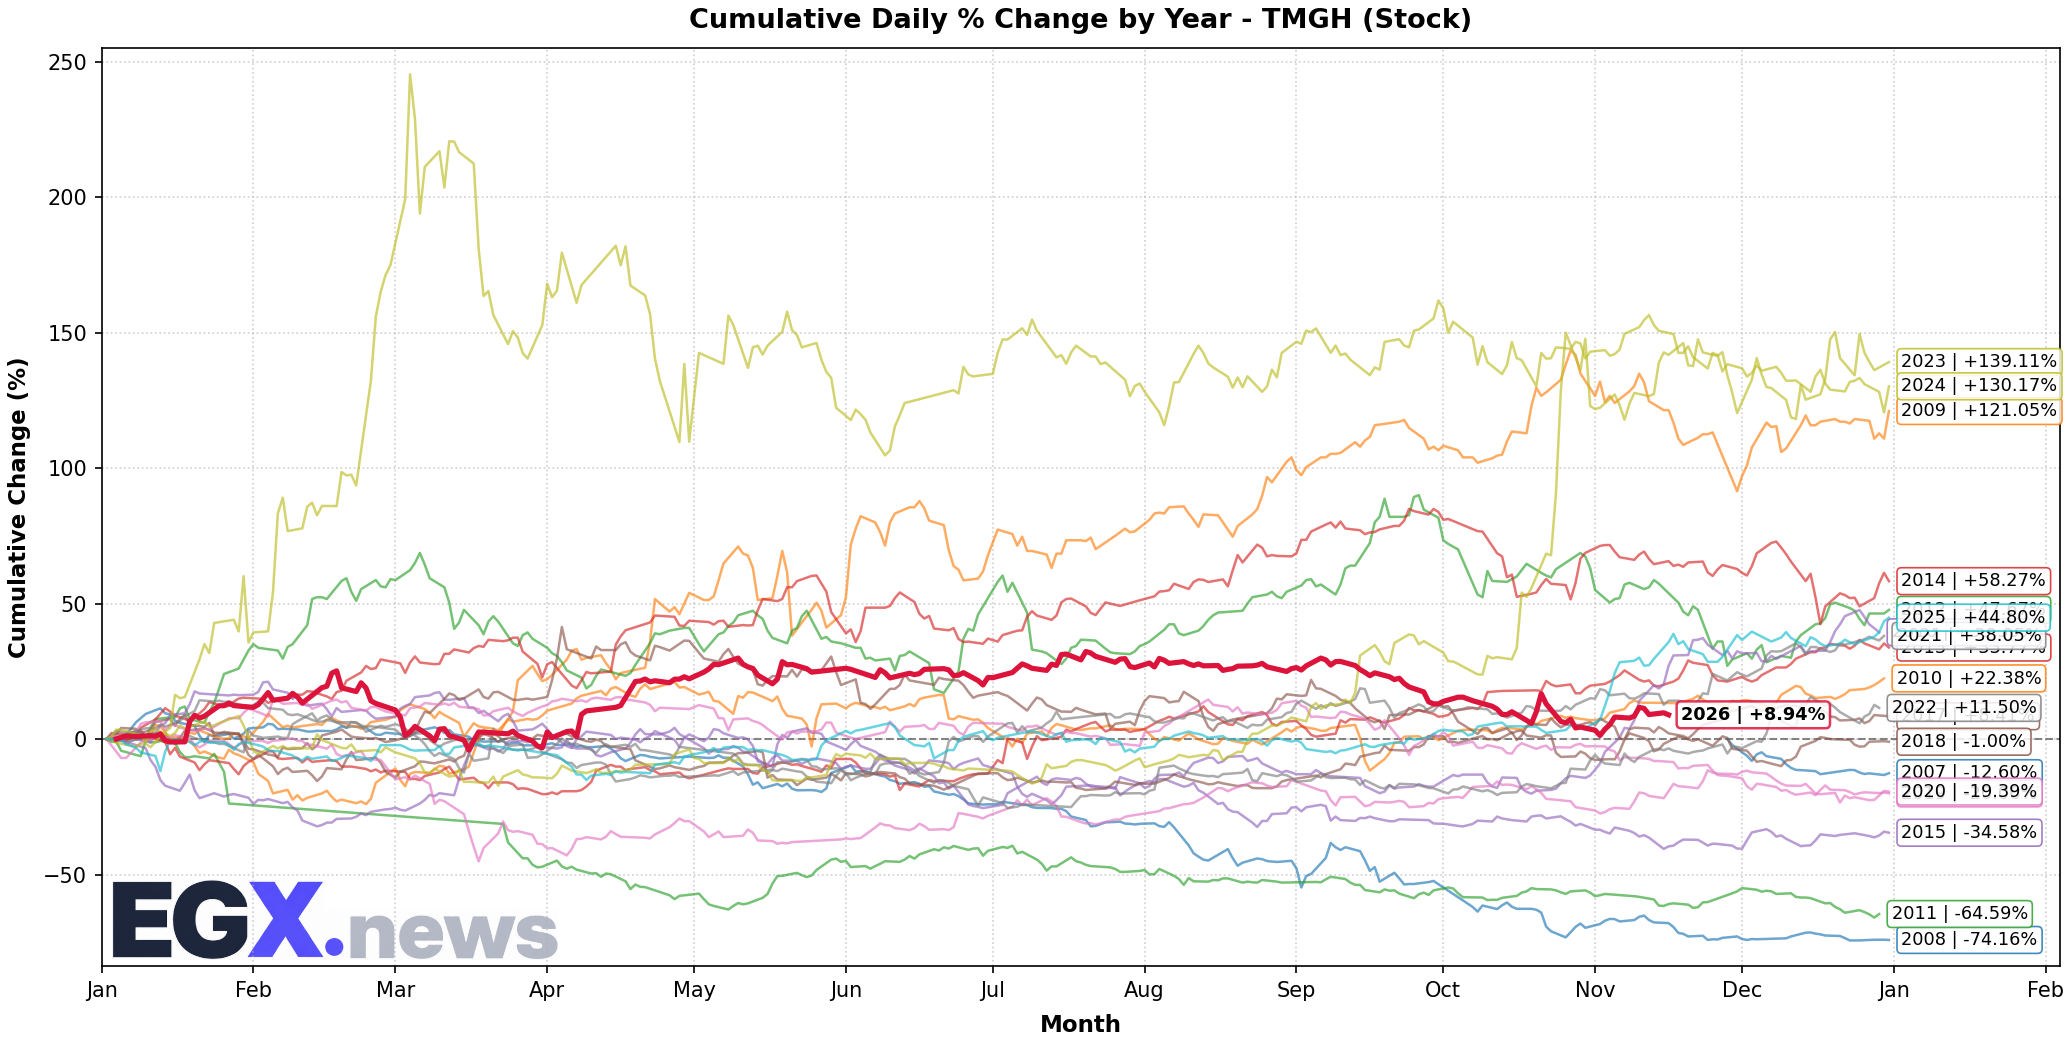
TMGH shares slipped 2.3% to close at EGP 14.80 amid sustained foreign‑investor selling pressure, while outlook points to continued challenges from higher mortgage‑funding costs. Charts show a clear break of support at EGP 15.50, with initial resistance at EGP 16.20, and the overall view remains negative unless the stock registers a strong rebound above the EGP 16 hurdle.
ABUK for Construction (ABUK) Stock
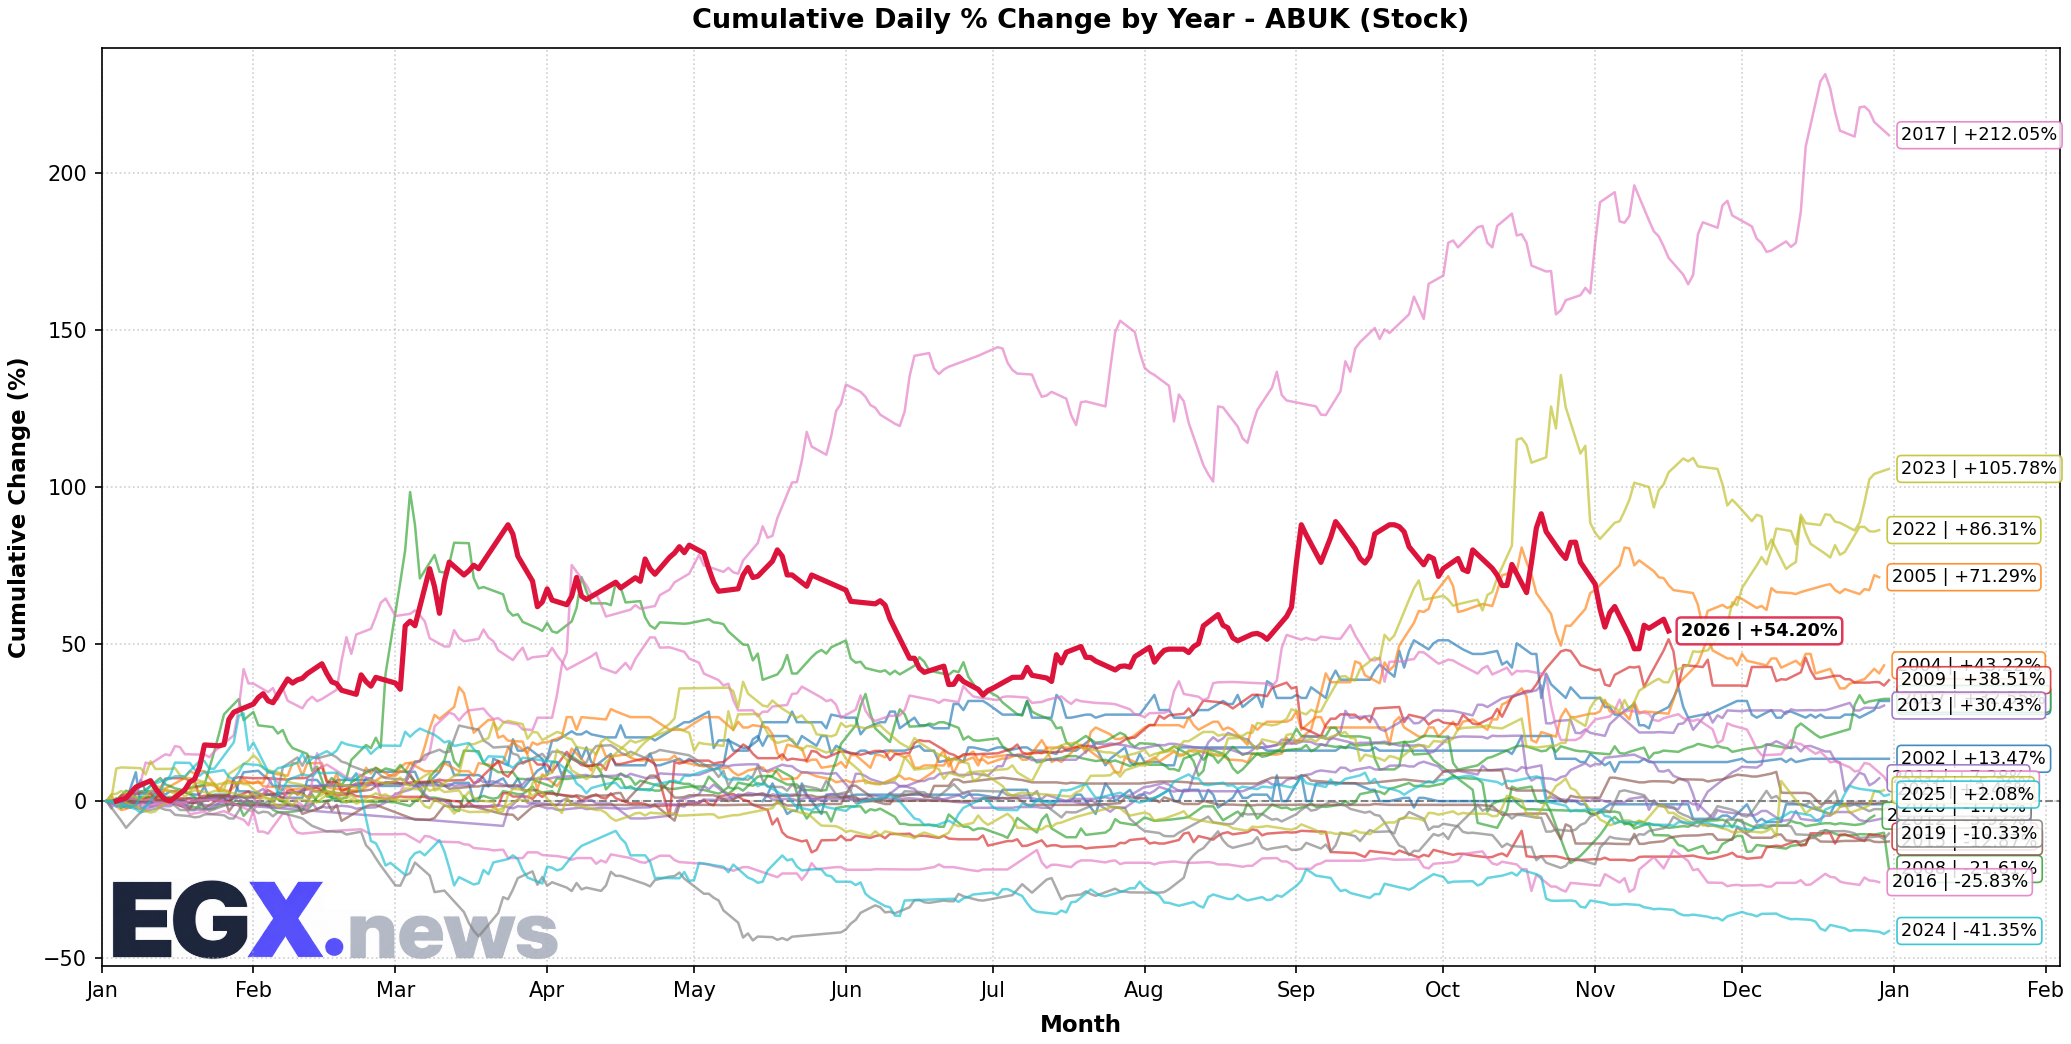
ABUK showed notable resistance around EGP 28.50 and ended the session virtually unchanged at EGP 28.30. The company retains a strong asset base and a diversified project pipeline, while investors watch the Egyptian central bank’s interest‑rate decision as a key near‑term driver for direction.
SWDY for Precision (SWDY) Stock
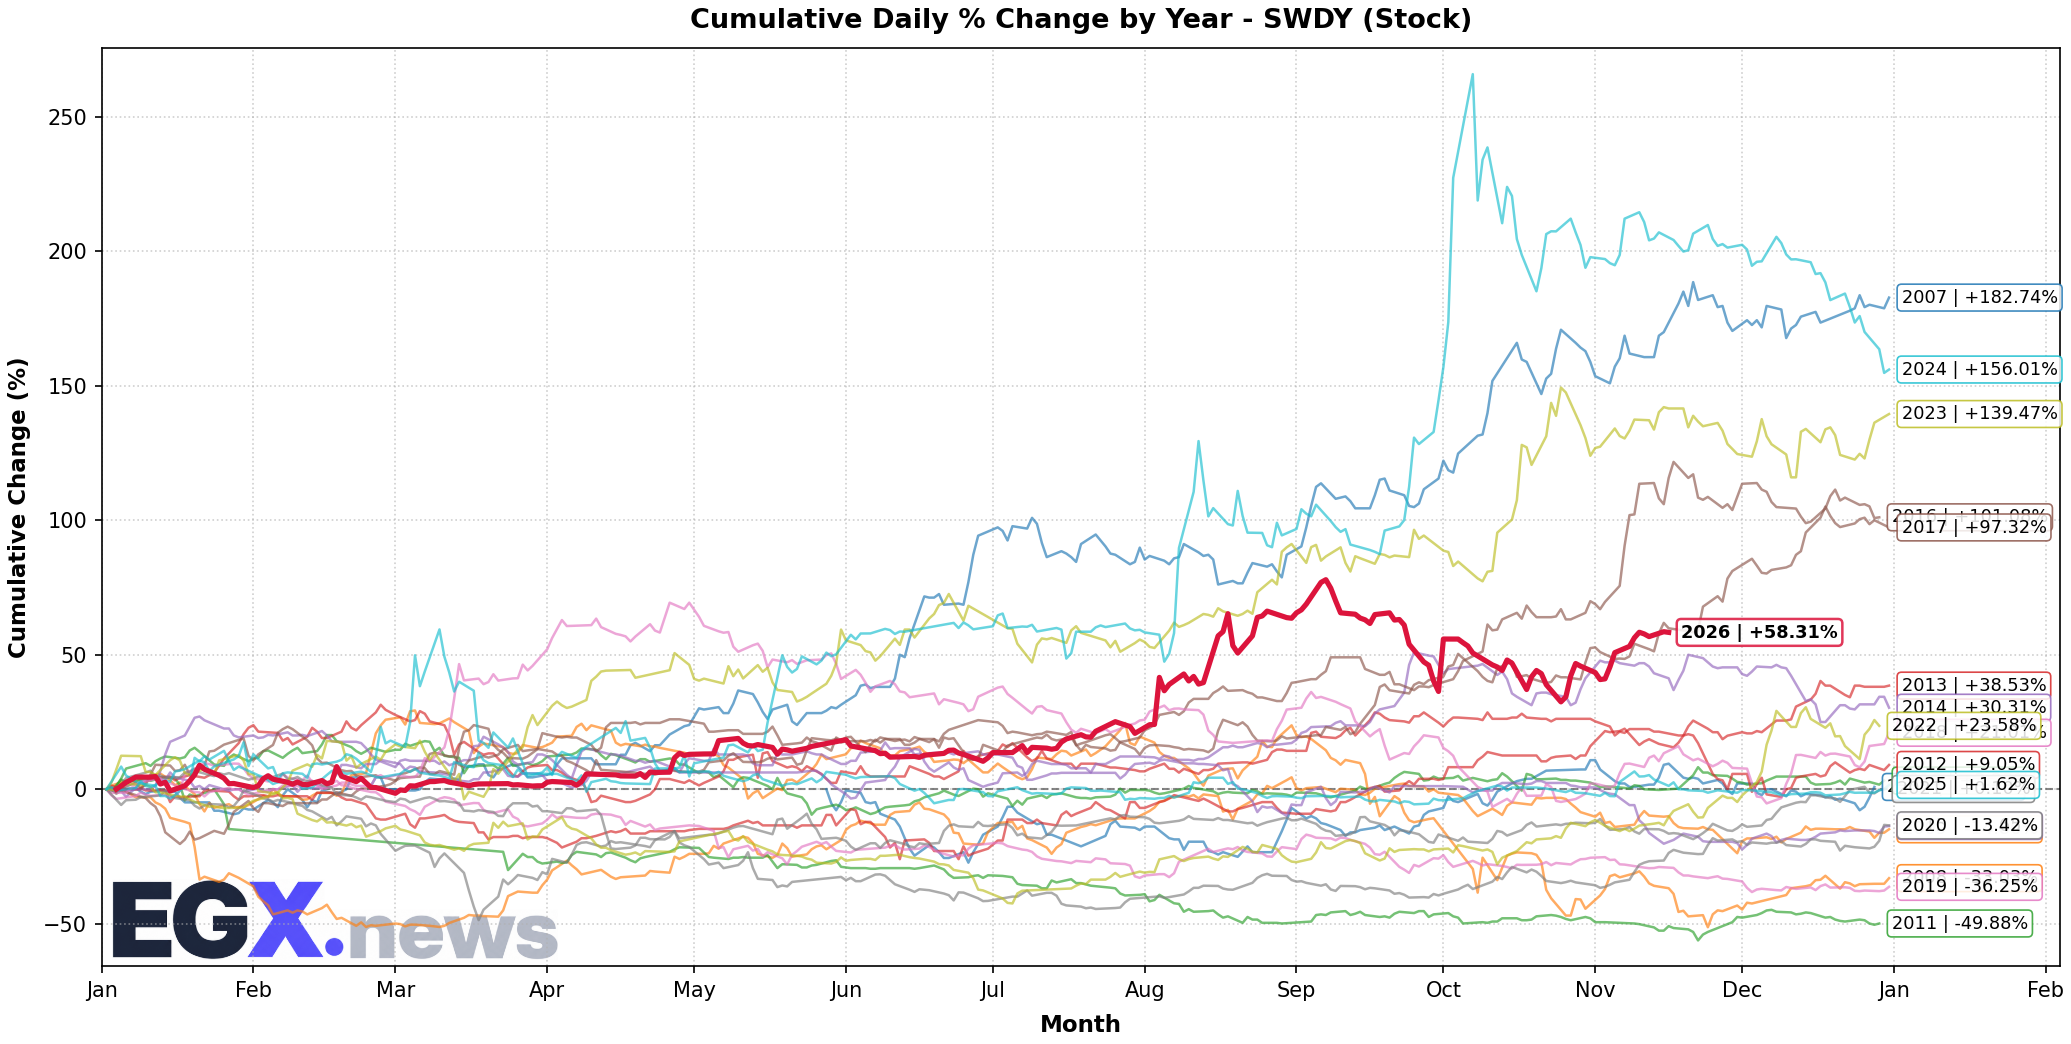
SWDY declined 1.7% to close at EGP 3.15, amid labor‑related pressures on the food sector; despite the company’s disclosed production‑line expansion plans, broader expectations suggest margins will be squeezed by higher input costs.
Global Geopolitical and Economic Factors
Global Interest Rates and Their Impact
The 30‑year US Treasury yield continued to post record levels at 5.44%, following the Federal Reserve’s tight stance and expectations of local rates holding steady. Economists anticipate the Egyptian central bank will maintain its current rate stance at its upcoming meeting.
Oil Prices and Regional Tensions
Oil prices jumped above $103 per barrel, buoyed by rising Middle East tensions and supply volatility, while Aramco expressed interest in exploring oil‑export options via Egypt, and the project proposes developing two new routes to strengthen the canal’s role in global supply chains.
Hot and Foreign Money Flows
The Egyptian market saw outflows of foreign and Arab capital amounting to roughly EGP 47.9 billion year‑to‑date, while remittances from Egyptians abroad rose to $4.5 billion in July, providing a fundamental support for the Egyptian pound and failing to offset foreign selling pressure on the exchange.
Conclusion and Outlook
The evening session on the Egyptian Exchange ended lower, driven by higher global bond yields, a firmer US dollar against the pound, and rising selling pressure on blue‑chip stocks. The EGX30 settled below the 55,000‑point threshold, while the EGX70 continued its drift toward the 2,100‑point area. Although local outlook remains cautious pending the central bank’s rate decision, technical indicators advise watching the 53,800‑point level as a critical support for the EGX30; conversely, the EGX70 must clear the 2,250‑point hurdle to resume an upward trend.
Egyptian banks continue to dominate market liquidity, while investors remain wary of global interest‑rate developments and growth prospects, noting that any shift in US Federal Reserve policy or an escalation of geopolitical tensions could disrupt the current trajectory of the Egyptian market.
Live Egyptian Equities Coverage
Track real-time quotes, order book market depth, and quantitative technical analytics for all 299 listed companies.
Open Real-Time Market Terminal →