


Morning Overview of the Egyptian Stock Exchange - 26 September 2026
Morning Overview of the Egyptian Stock Exchange - 26 September 2026
---
Introduction
Today's session begins amid a tense global environment showing notable rises in US Treasury yields and continuing geopolitical concerns between Washington and Tehran. Conversely, the Egyptian central bank holds interest rates steady for the fifth consecutive meeting, with expectations of inflation stabilising in Q3 despite external pressures. Energy attracts investor focus after BP announced a $700 million investment to drill four confirmed wells in Egypt and Chevron’s plans to expand exploration and production activities.
---
Analysis of Macroeconomic Indicators
Latest data indicate Egypt's inflation rate is moving toward stability, as the central bank confirmed the downward inflation trend supports maintaining the current monetary stance. Meanwhile, global markets remain negative toward the rise in US 30‑year Treasury yields to levels not seen since 2004, increasing risk aversion in emerging markets.
Key Quote: “Holding rates is the most likely scenario in today’s central bank meeting” reflects the market’s tilt toward short‑term monetary stability, while external risks continue to stimulate capital outflows.
On the price front, the US dollar edged higher against the Egyptian pound in early trade but later retreated as hot money inflows supported the local currency. Gold remains under dual pressure from rising US rates and oil volatility, with the pricing gap gradually narrowing.
---
Analysis of Egyptian Stock Exchange Indices
Main Index

The main index of the Egyptian bourse trades in a tight range around the 54,500‑point level, with a slight downward bias due to institutional selling pressure and foreign liquidity outflows. Performance hinges on a balance between optimism in the energy sector and investor fear of escalating geopolitical tensions.
Small‑Cap Index

The small‑cap index exhibits higher volatility compared to the main index, posting a decline of roughly 2 % in the previous session. This move is attributed to the sensitivity of mid‑ and small‑cap stocks to hot‑money liquidity swings and the impact of interest rates on financing costs.
Technical Note: The main index’s health shows a reading of 36/100, indicating a market lacking a clear direction, while the advance‑decline ratio (27.9 % vs 47.5 %) points to short‑term negative momentum dominance.
---
Analysis of Core Stocks
Commercial International Bank (COMI)

COMI benefits from the steady interest‑rate environment, which eases borrowing costs, alongside expectations of strong loan‑book growth underpinned by new energy projects. The stock displays a moderate positive bias, supported by institutional liquidity shifting toward the financial sector.
Talaat Moustafa Group (TMGH)
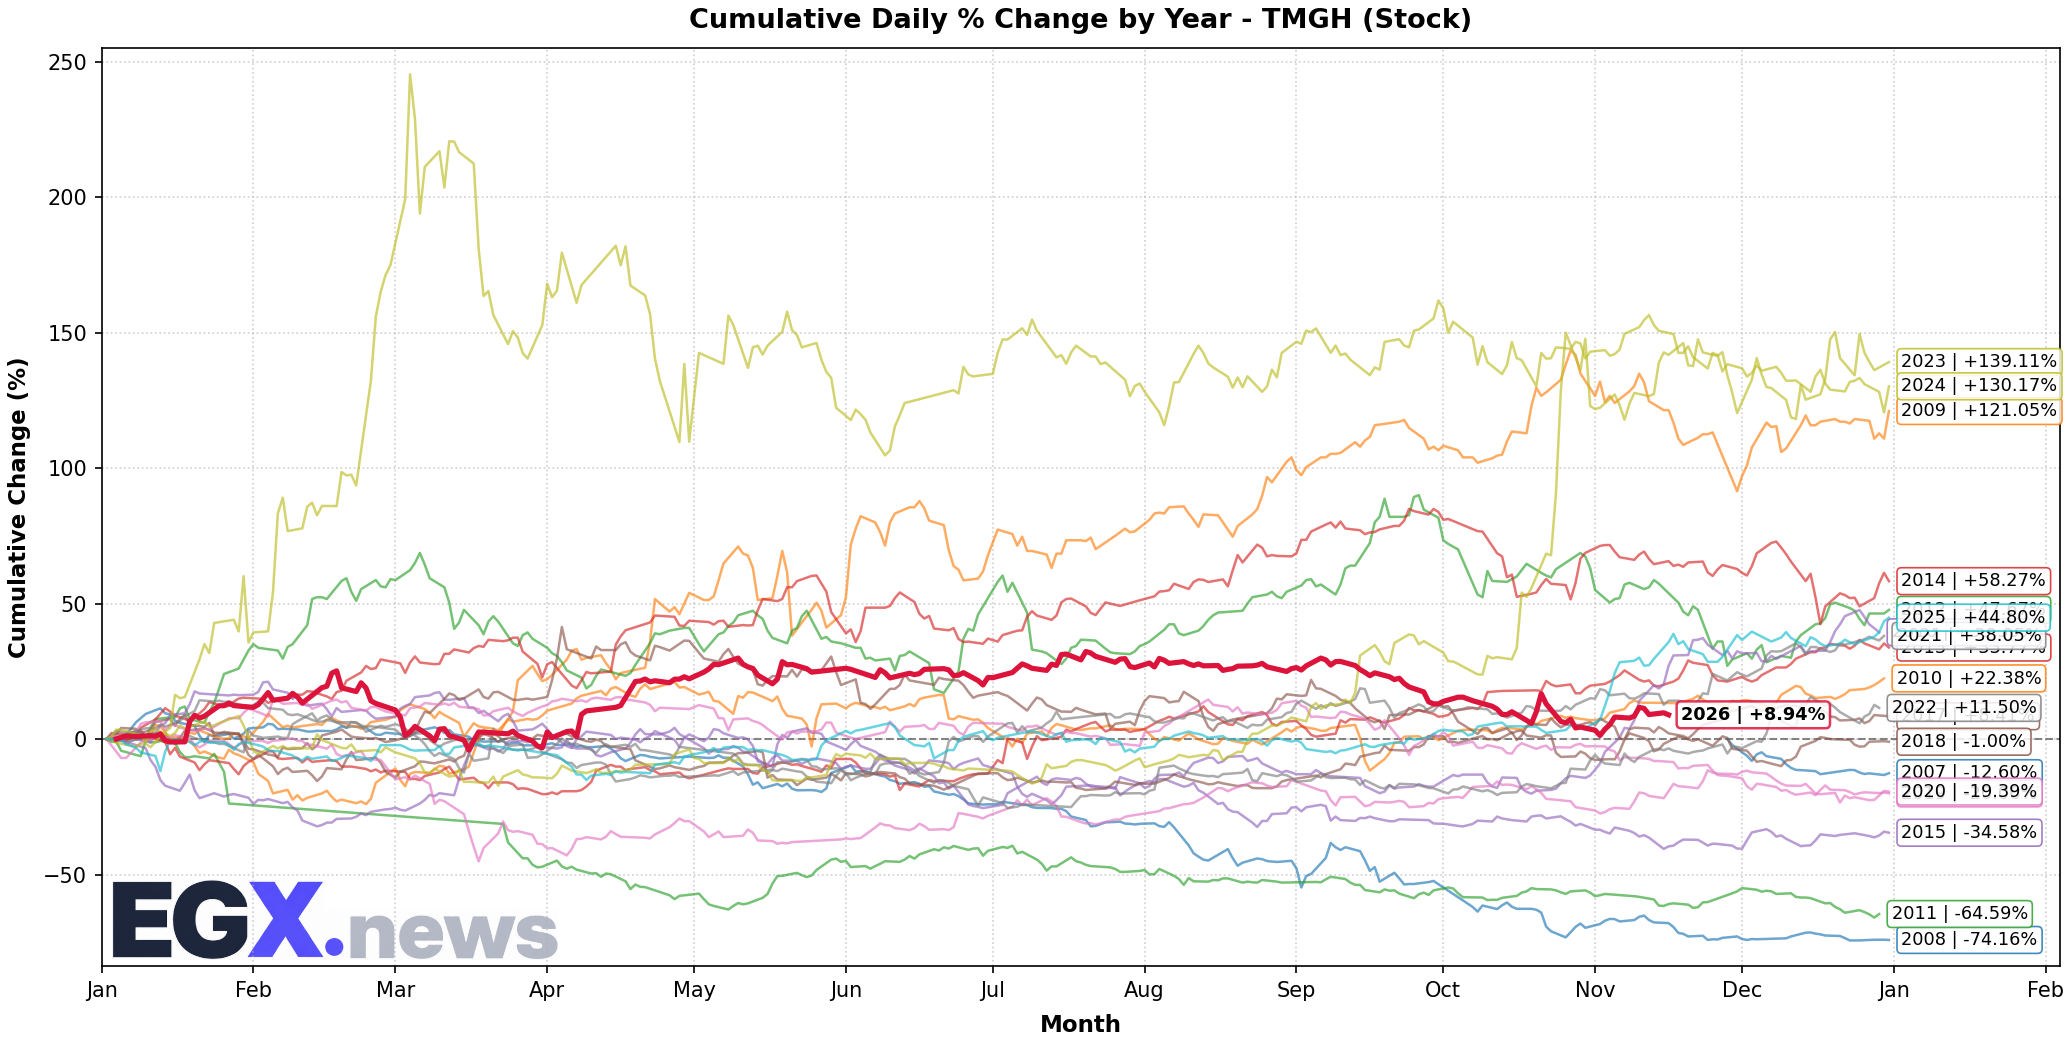
The group faces pressure from slowing real‑estate activity and higher financing costs, leaving the stock vulnerable to further declines should the property downturn persist. Investors await any signs of recovery in residential and commercial demand.
Abou Kir Fertilizers & Chemicals Industries (ABUK)
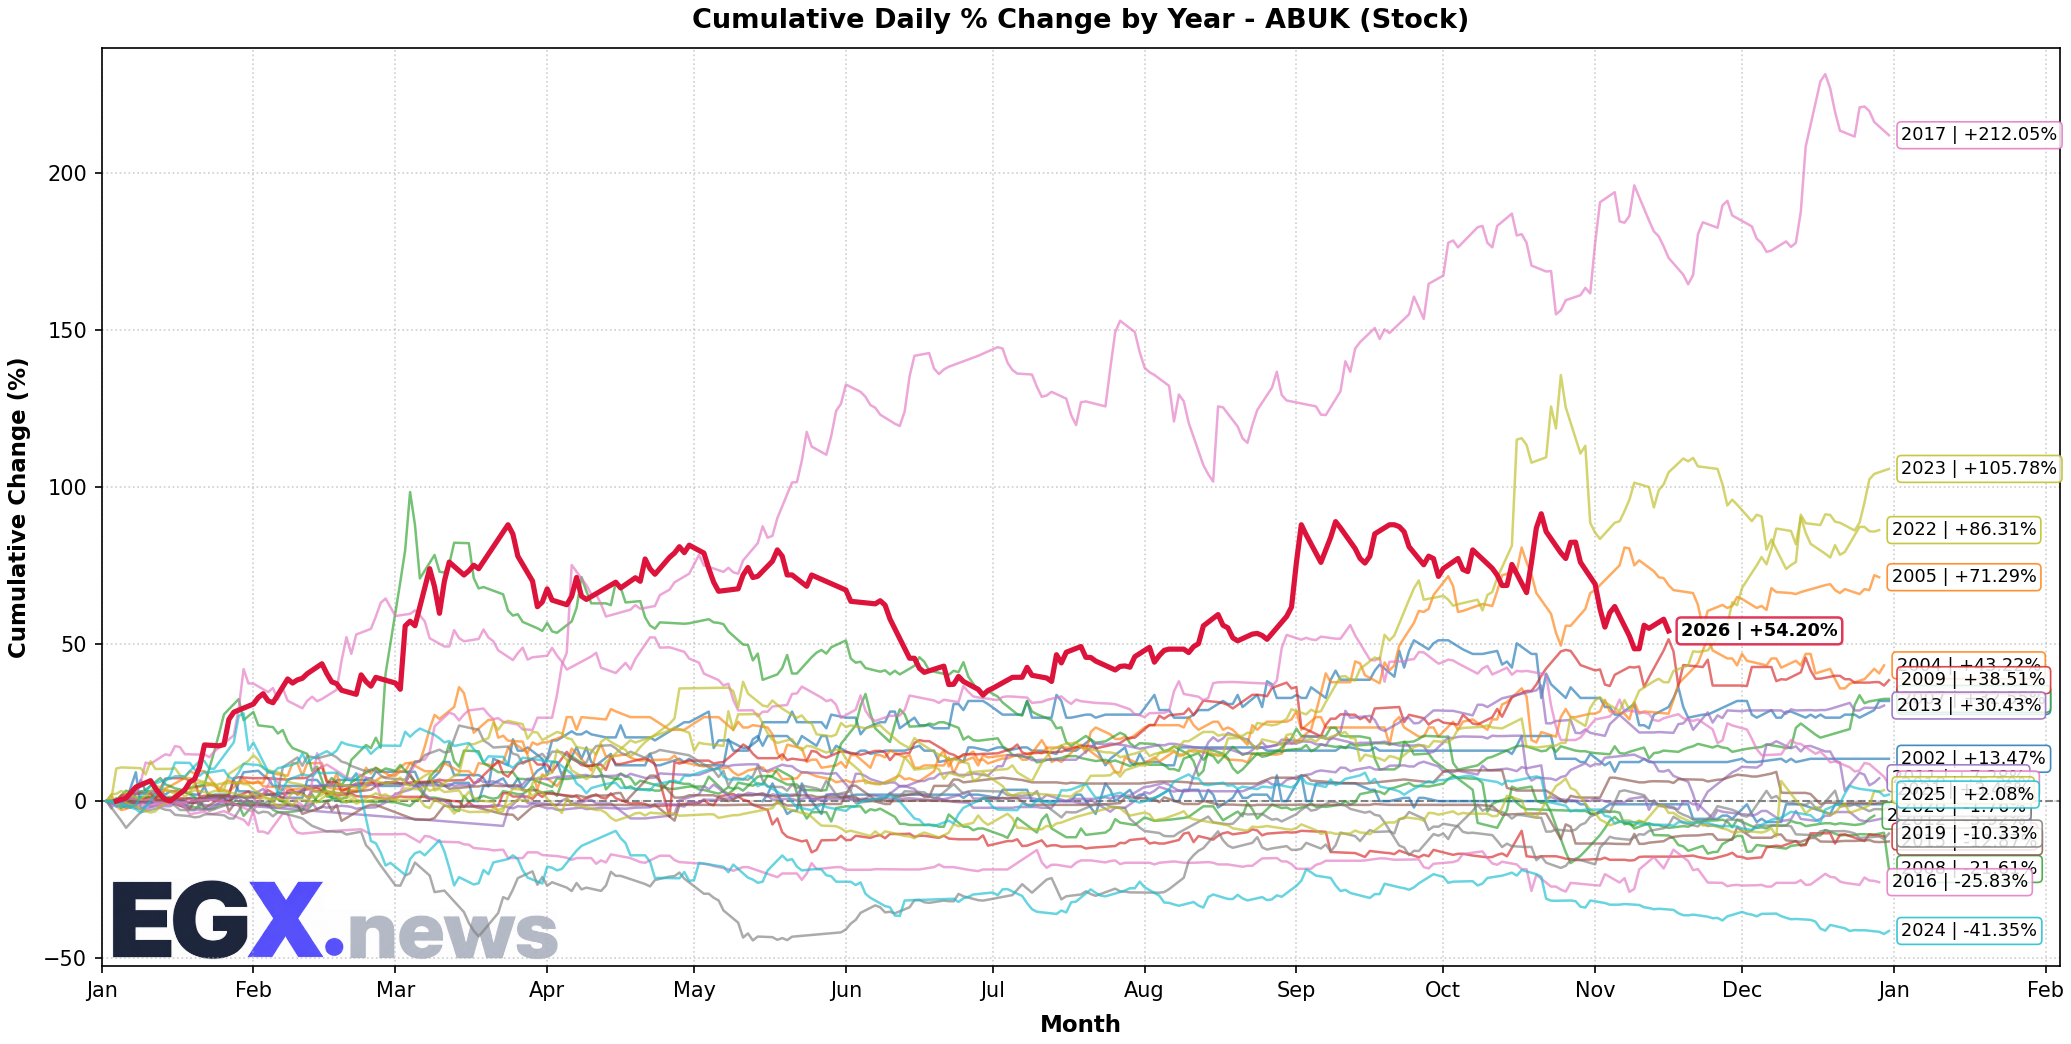
ABUK gains from stable gas prices and the expansion of export projects to European and Asian markets. A strong financial position and solid liquidity enable the company to weather short‑term commodity price swings.
El Sewedy Electric (SWDY)
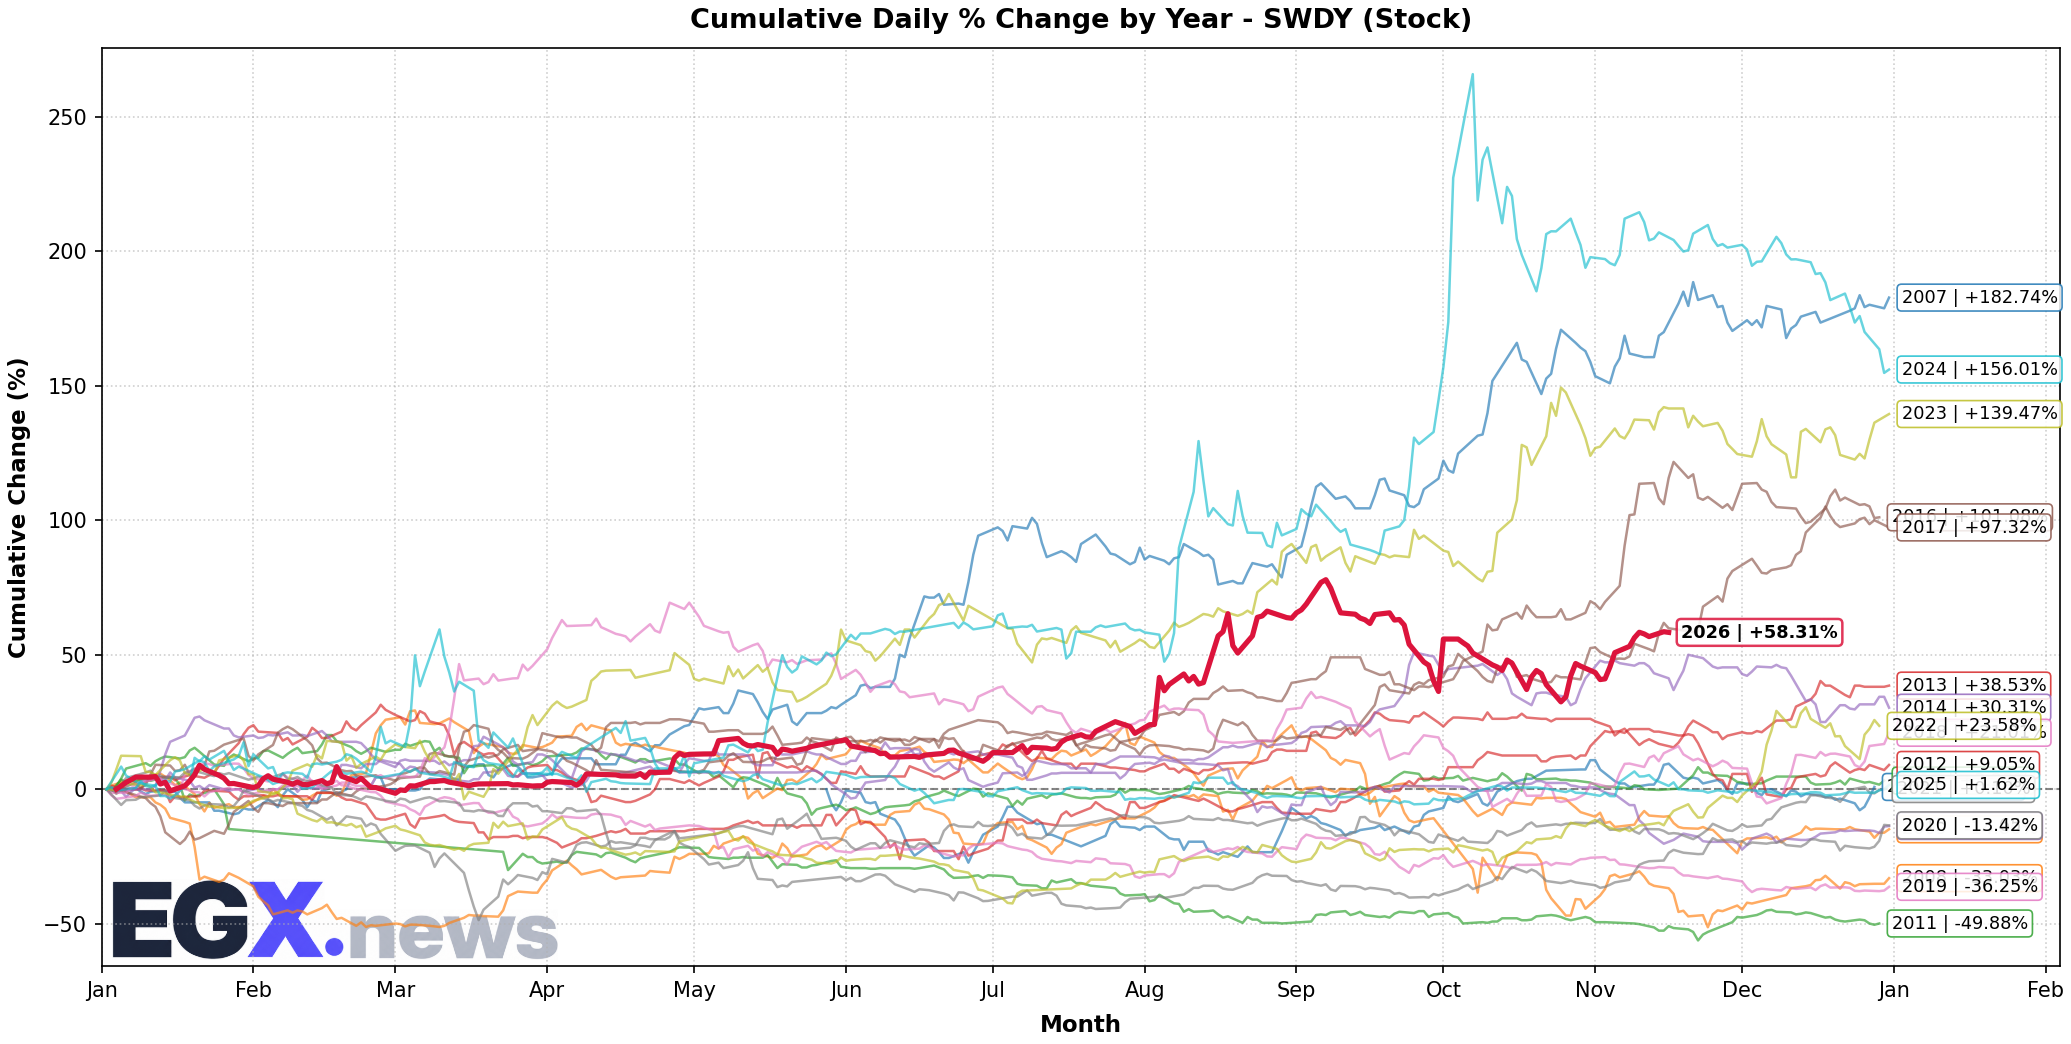
SWDY is experiencing rising demand for its products in the renewable‑energy and smart‑systems sectors, creating growth opportunities as borrowing costs stabilise. Performance depends on the firm’s ability to execute agreed‑upon supply contracts with international partners.
Strategic Quote: “Investing in the energy sector breeds long‑term confidence, while the real‑estate sector remains sensitive to interest‑rate shifts and local demand.”
---
Session‑Opening Expectations
Based on the foregoing, the market is expected to open quietly with a mild bearish tilt in the main index, stemming from persistently high US yields and pressure on finance‑linked stocks. Activity in energy shares could lend some support, especially if news of BP and Chevron expansions continues to draw local liquidity.
From a technical perspective, should the main index close above the 55,000‑point level it may signal an attempt to regain confidence; a break below 53,500 points could steer the market toward testing support at 52,800 points.
---
Summary and Recommendations
- Monetary Policy: Holding rates provides a low‑cost borrowing environment in the short term, yet does not erase external pressures.
- Energy Sector: BP and Chevron investments bolster revenue expectations for linked logistics and financial firms, potentially bolstering stocks such as COMI.
- Real‑Estate Sector: Remains prone to further declines amid rising financing costs and weak demand; caution advised in positions like TMGH.
- Core Stocks: ABUK and SWDY offer a balance between commodity exposure and technology, potentially serving as a relative haven against sharp volatility.
Investors should monitor any shift in US Treasury yield trajectories and any developments in US‑Iran negotiations, as these factors remain primary drivers of market direction in upcoming sessions.
---
Live Egyptian Equities Coverage
Track real-time quotes, order book market depth, and quantitative technical analytics for all 299 listed companies.
Open Real-Time Market Terminal →