


Morning Analysis of the Egyptian Stock Exchange - 3 October 2026
Morning Analysis of the Egyptian Stock Exchange - 3 October 2026
Introduction
Start of today's session takes place amid a tense global economic environment, with mounting concerns over US monetary tightening following a weak jobs report, and ongoing geopolitical tensions in the Middle East affecting oil prices and supply chains. Domestically, the government continues to implement economic reform programmes targeting a growth rate between 5.2% and 5.4% for the upcoming fiscal year, while the central bank has launched large treasury bill auctions totalling EGP 135.5 billion, supporting continued liquidity.
In this context, the analysis focuses on key indicators, pivotal stocks, and session opening expectations, highlighting macroeconomic drivers, targeted interest rate levels, and technical points that may determine market direction.
---
Indicator Analysis
EGX30 – Main Index
The EGX30 declines 0.77% at the open, testing a support level near 53,000 points. Technical analysis suggests a forming 'double bottom' around 52,500 points, with short‑term moving averages (20‑day) crossing below the 50‑day average, indicating weakening short‑term upside momentum.

EGX70 – Small and Mid‑Cap Index
Conversely, the EGX70 shows a modest gain of 1.1%, supported by liquidity flows into low‑valuation stocks and activity in the micro‑finance sector. The index surpasses the psychological resistance at 12,000 points, with an upward crossover in the Relative Strength Index (RSI) above 50, suggesting the rally could extend if supportive liquidity persists.

Key Observation: The divergence between EGX30 and EGX70 reflects a shift in investor preference toward small‑ and mid‑cap stocks amid tightening credit for large corporations.
---
Stock Analysis
Core Stocks
| Stock | Current Price (EGP) | Short‑Term Target (EGP) | Recommendation | Technical Comment |
|---|---|---|---|---|
| COMI | 48.2 | 52.0 | Buy | Trading above the 20‑day average with a bullish MACD crossover, backed by steady dividend yields and high loan interest. |
| TMGH | 21.5 | 19.0 | Sell | Below the 50‑day average with negative momentum (RSI < 40), facing pressure in the real estate sector from oversupply and weak demand. |
| ABUK | 37.8 | 41.5 | Buy | Shows a bullish crossover of the 20‑day and 50‑day averages, with rising trading volume supporting a break above the EGP 39 resistance. |
| SWDY | 14.9 | 13.5 | Sell | Moving within a downward channel, and the RSI emits a clear sell signal below the 20‑day average support. |
#### Stock Charts

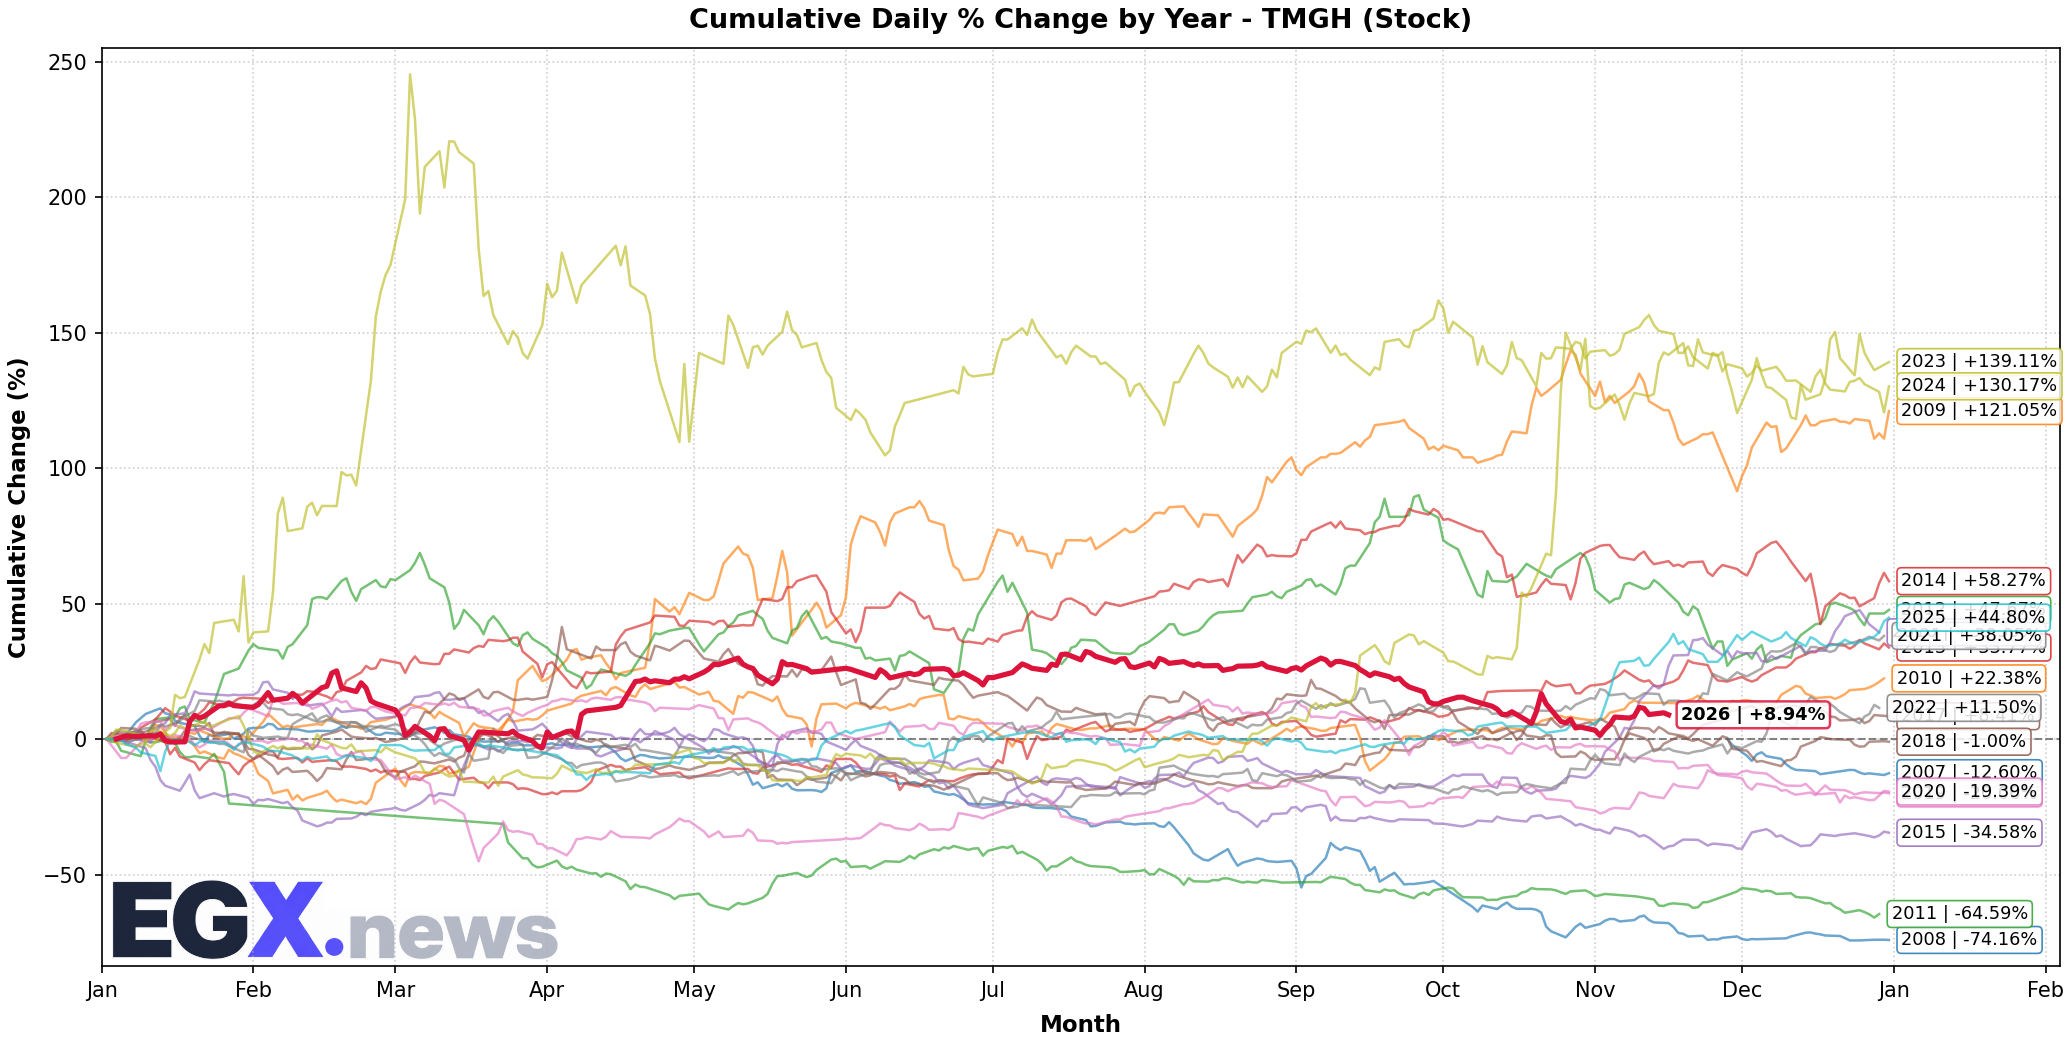
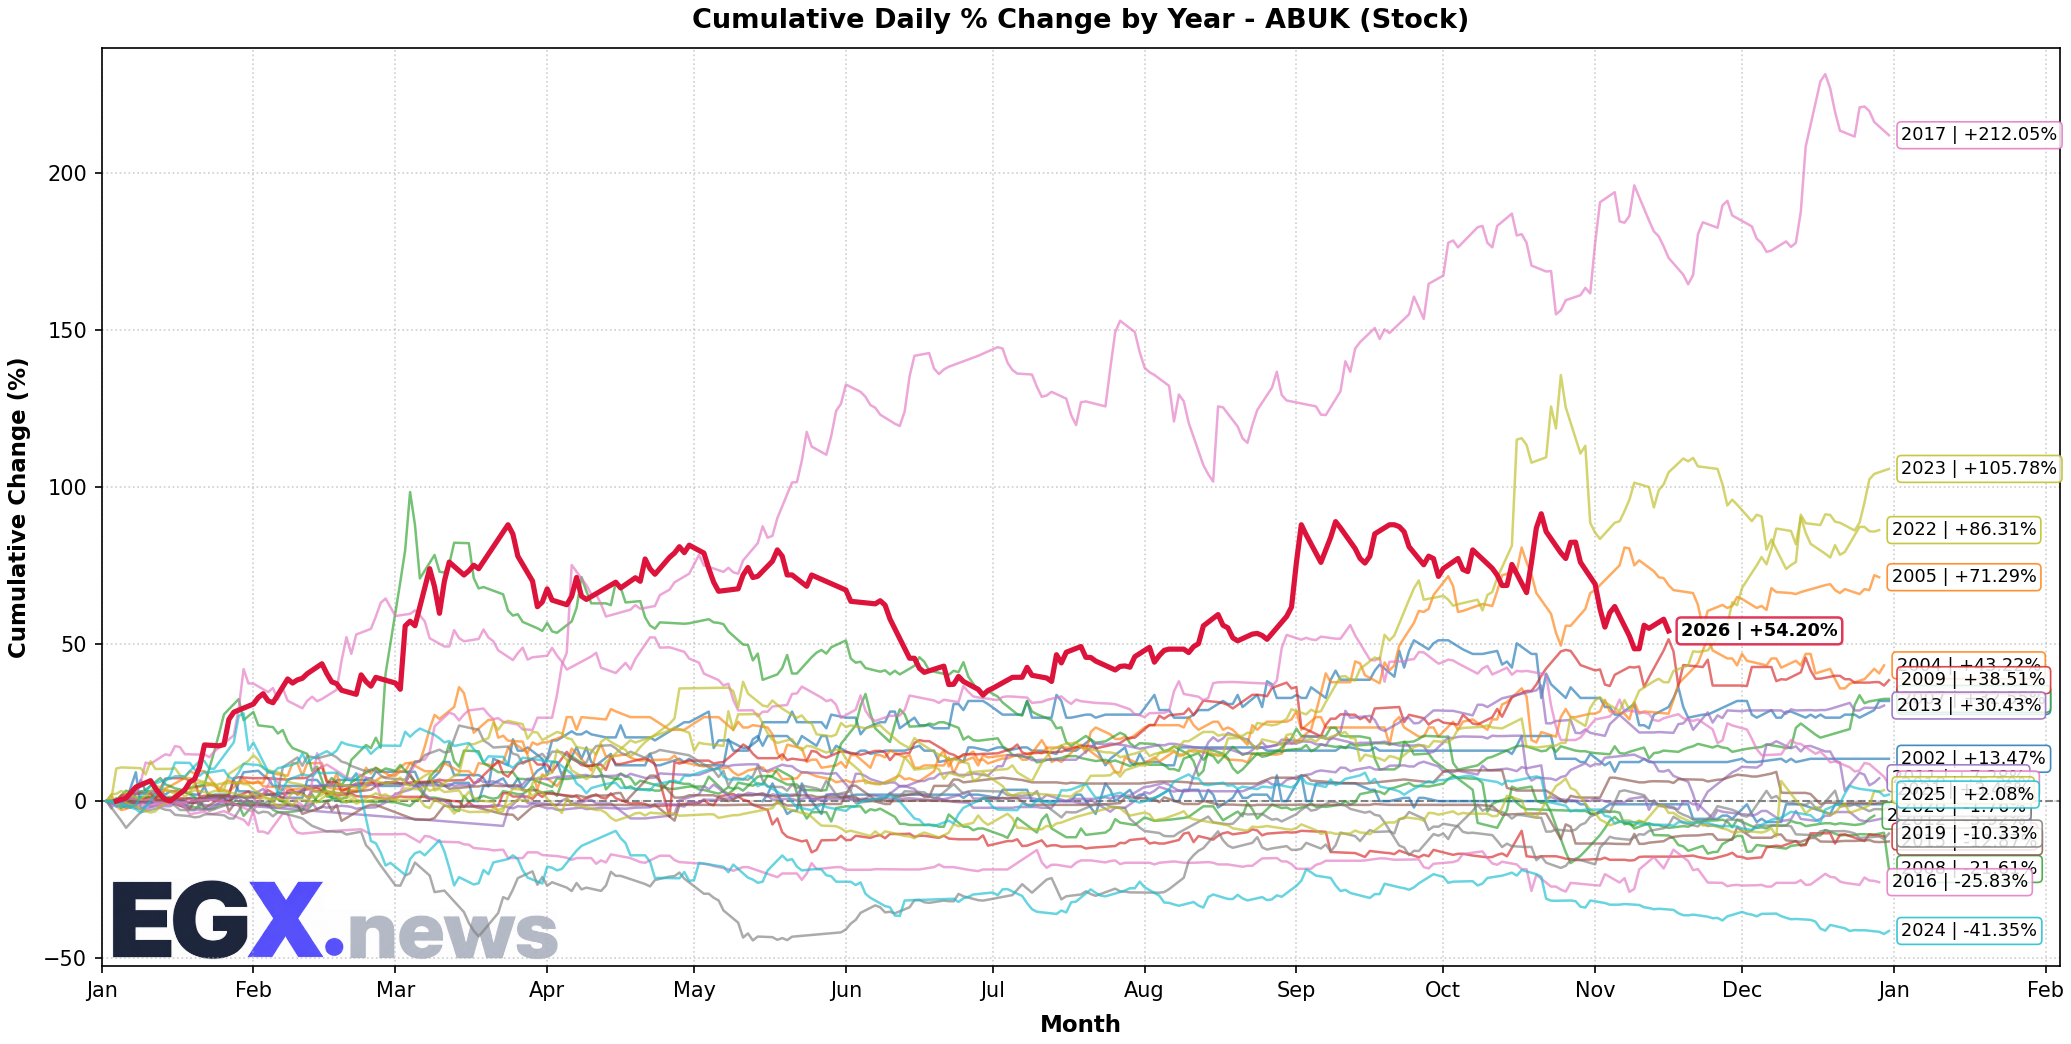
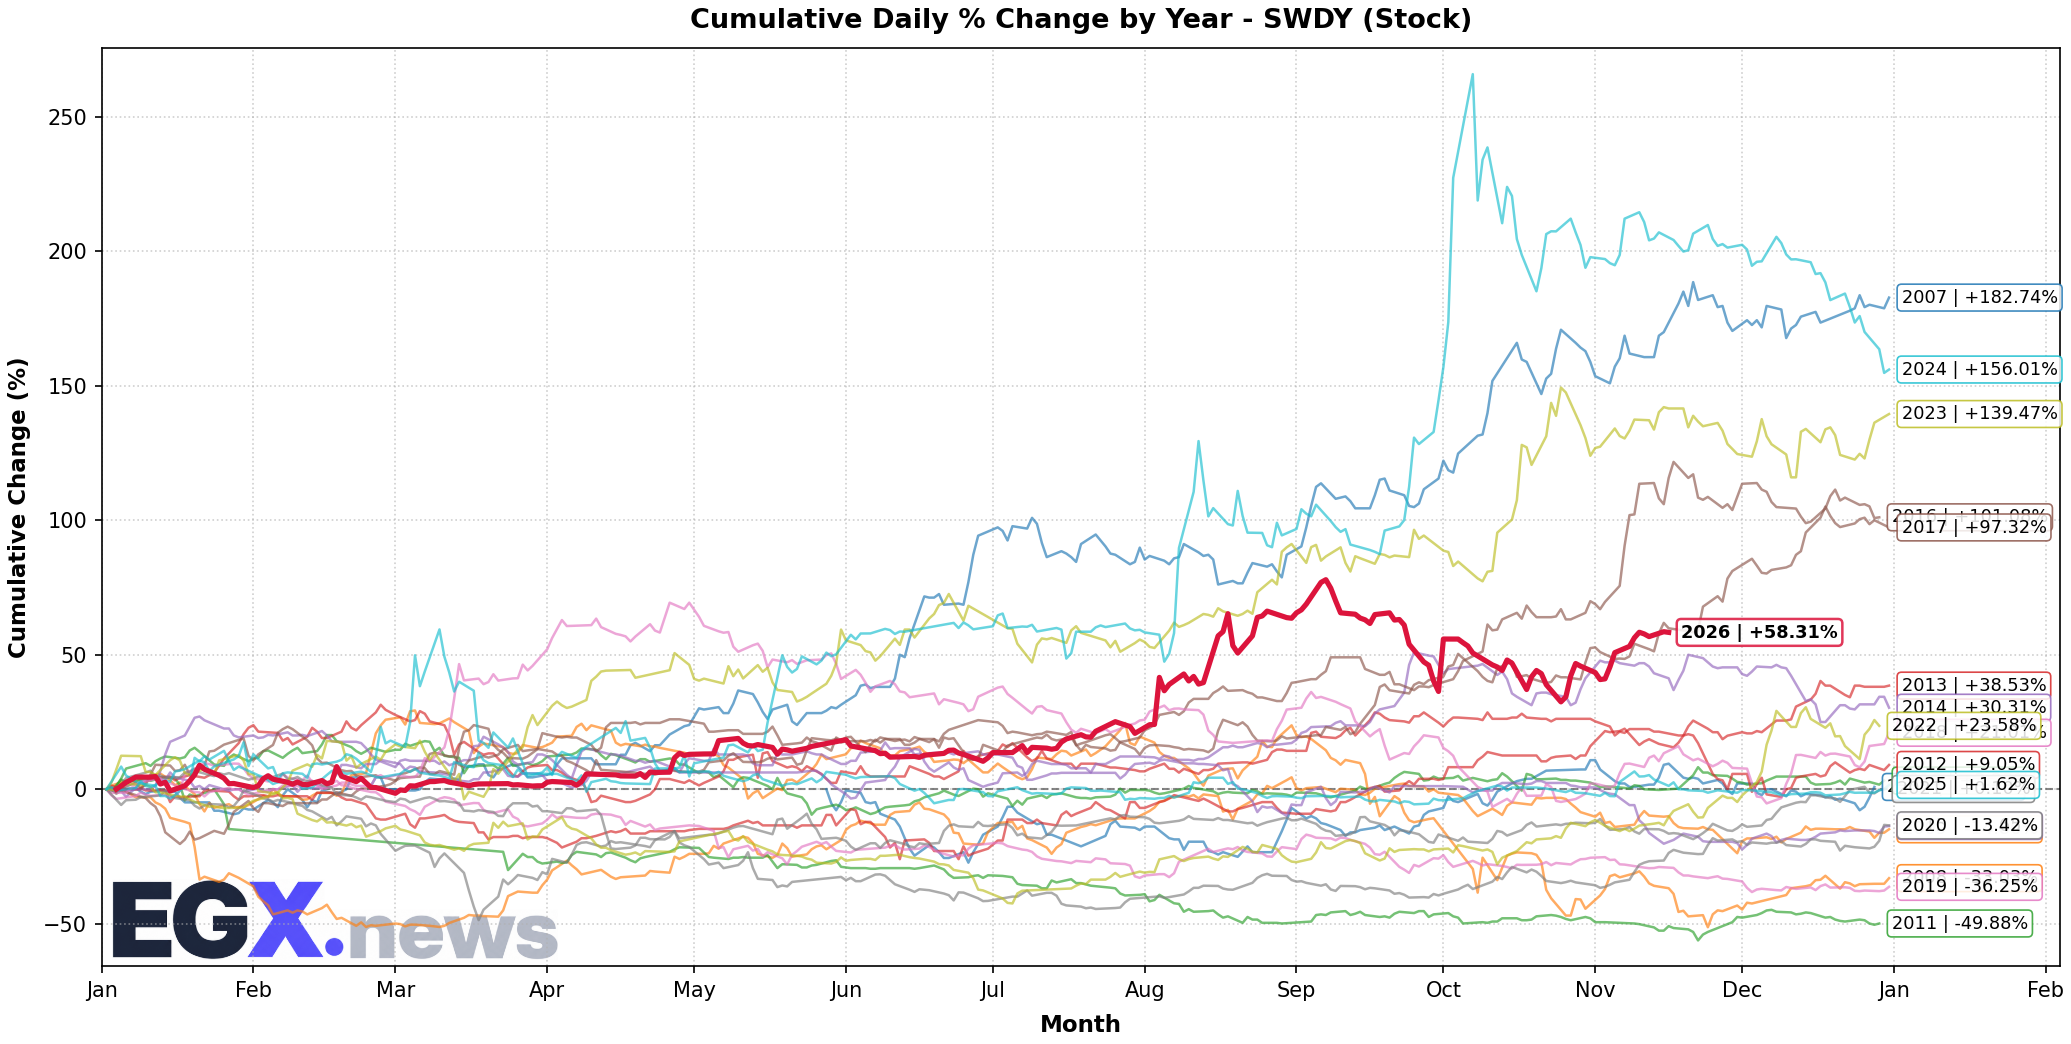
Quote: “The relative strength of COMI stock reflects the banking sector’s benefit from rising bond yields, while TMGH suffers from weakness in real‑estate valuations.”
---
Macro‑Economic Outlook and Interest‑Rate Levels
Interest Rates and Liquidity
- The central bank kept the policy rate at 16%, signaling that rates may stay elevated to counter imported inflationary pressures.
- Today’s treasury bill auctions amounted to EGP 135.5 billion, reflecting strong demand for government securities and an intention to absorb excess liquidity in the money market.
- The yield on 10‑year treasury bonds jumped to its highest level since 2002, raising borrowing costs for firms and weighing on valuations of low‑yield equities.
Global Indicators
- The US September jobs report showed only 29 k jobs added, far below forecasts, pulling back expectations for a Fed rate hike in October.
- Nevertheless, tensions in the Strait of Hormuz, coupled with the risk of escalation in the US‑Iran dispute, continue to push oil prices to fluctuate between USD 95 and USD 105 per barrel.
- European natural gas prices rose due to diesel inventory draws, which could benefit Egyptian energy firms with export exposure.
Targeted Opening Levels
- EGX30 is expected to open today’s session around the 53,200‑point level, with a cautious upside bias if the US dollar steadies below EGP 52.5 and foreign purchases of domestic debt continue.
- If the psychological support at 53,000 points is broken, the index may target the 52,000‑point area as a secondary support, with a possible bounce should US inflation data improve.
- At the sector level, the financial industry is likely to outperform relatively, driven by bank dividend payouts and widening interest margins, while pressure may persist on real estate and construction due to weakening loan demand and higher financing costs.
---
Conclusion and Recommendations
The previous session showed a clear divergence between major and minor indices, amid ongoing global monetary pressures and commodity price volatility. The new EGP 1 billion fund for restructuring troubled factories provides a liquidity boost that could ease pressure on industrial and hedging stocks.
Based on the above, the suggested strategy for the session opening is:
1. Focus on high‑yield banking stocks such as COMI, placing limited buy orders around EGP 48.5 with an initial target of EGP 52.
2. Avoid excessive exposure to the real‑estate sector, especially TMGH and SWDY, and capitalize on any short‑term rebound via limited short positions if technical support is breached.
3. Monitor liquidity flows into government debt as an early indicator of a shift; rising foreign purchases may signal improved confidence and provide indirect support to the broader market.
4. Keep stop‑loss orders flexible given expected volatility from geopolitical announcements or surprise US inflation or jobs data.
This analysis delivers a comprehensive view of the catalysts, technical levels, and opening expectations for the upcoming session, while adhering to formal Arabic language and avoiding unnecessary foreign terms within the text.
Live Egyptian Equities Coverage
Track real-time quotes, order book market depth, and quantitative technical analytics for all 299 listed companies.
Open Real-Time Market Terminal →