


Morning Summary of the Egyptian Stock Exchange: Analysis of Indicators and Leading Stocks - 13 October 2026
Introduction
The morning session sees cautious trading amid a clear divergence between the main and subsidiary indices. Yesterday's performance reflected a decline of 1.14% for the EGX30 and a sharper drop of 4.33% for the EGX70, indicating selling pressure on small- and mid-cap stocks. At the same time, some macro data show support for export-oriented and banking sectors, especially after recording a surplus in the balance of payments of $2.8 billion in the past fiscal year and progress in sales of the WEST project.
Indices Analysis
EGX30

The main index closed at 22,450 points after a loss of 1.14%. The price is currently trading below the 20‑day average of 22,800 points, but remains above strong support at 22,000 points resulting from institutional demand for major bank stocks. Technically, a descending triangle is forming with resistance at 22,800 points and support at 22,200 points; breaking support could open the way to target 21,600 points as the first downside target.
EGX70

The 70‑index fell to 5,820 points, recording a decline of 4.33%. The price breaks below the 50‑day average of 6,050 points and heads toward psychological support at 5,600 points. Momentum indicators (RSI) show values near 30, reflecting oversold conditions that could allow a rebound if buying pressure on resilient mid‑cap stocks emerges at this level.
Performance Comparison
| Index | Close (Pts) | Daily Change | 20‑Day Avg | Near Support | Near Resistance |
|---|---|---|---|---|---|
| EGX30 | 22,450 | -1.14% | 22,800 | 22,200 | 22,800 |
| EGX70 | 5,820 | -4.33% | 6,050 | 5,600 | 6,200 |
Technical Note: Stock contact at the support levels shown above could form a launch point for operations if accompanied by improvement in local inflation data or stabilization of the dollar price.
Core Stocks Analysis
Commercial International Bank (COMI)

The stock closed at EGP 63.20 after a slight rise of 0.4%, driven by expectations that the bank will benefit from the balance‑of‑payments surplus and stable interest rates. Daily trading volume of about 1.2 million shares reflects domestic and international interest in the financial sector. Fundamentally, the price‑to‑book ratio (P/B) is around 1.2, while the expected earnings per share (EPS) for the coming fiscal year is EGP 5.8, implying a dividend yield of approximately 9%. Technically, the stock trades within a narrow ascending channel with support at EGP 62.00 and resistance at EGP 65.00; breaking resistance could push the stock toward a medium‑term target of EGP 70.00.
Talaat Moustafa Group (TMGH)
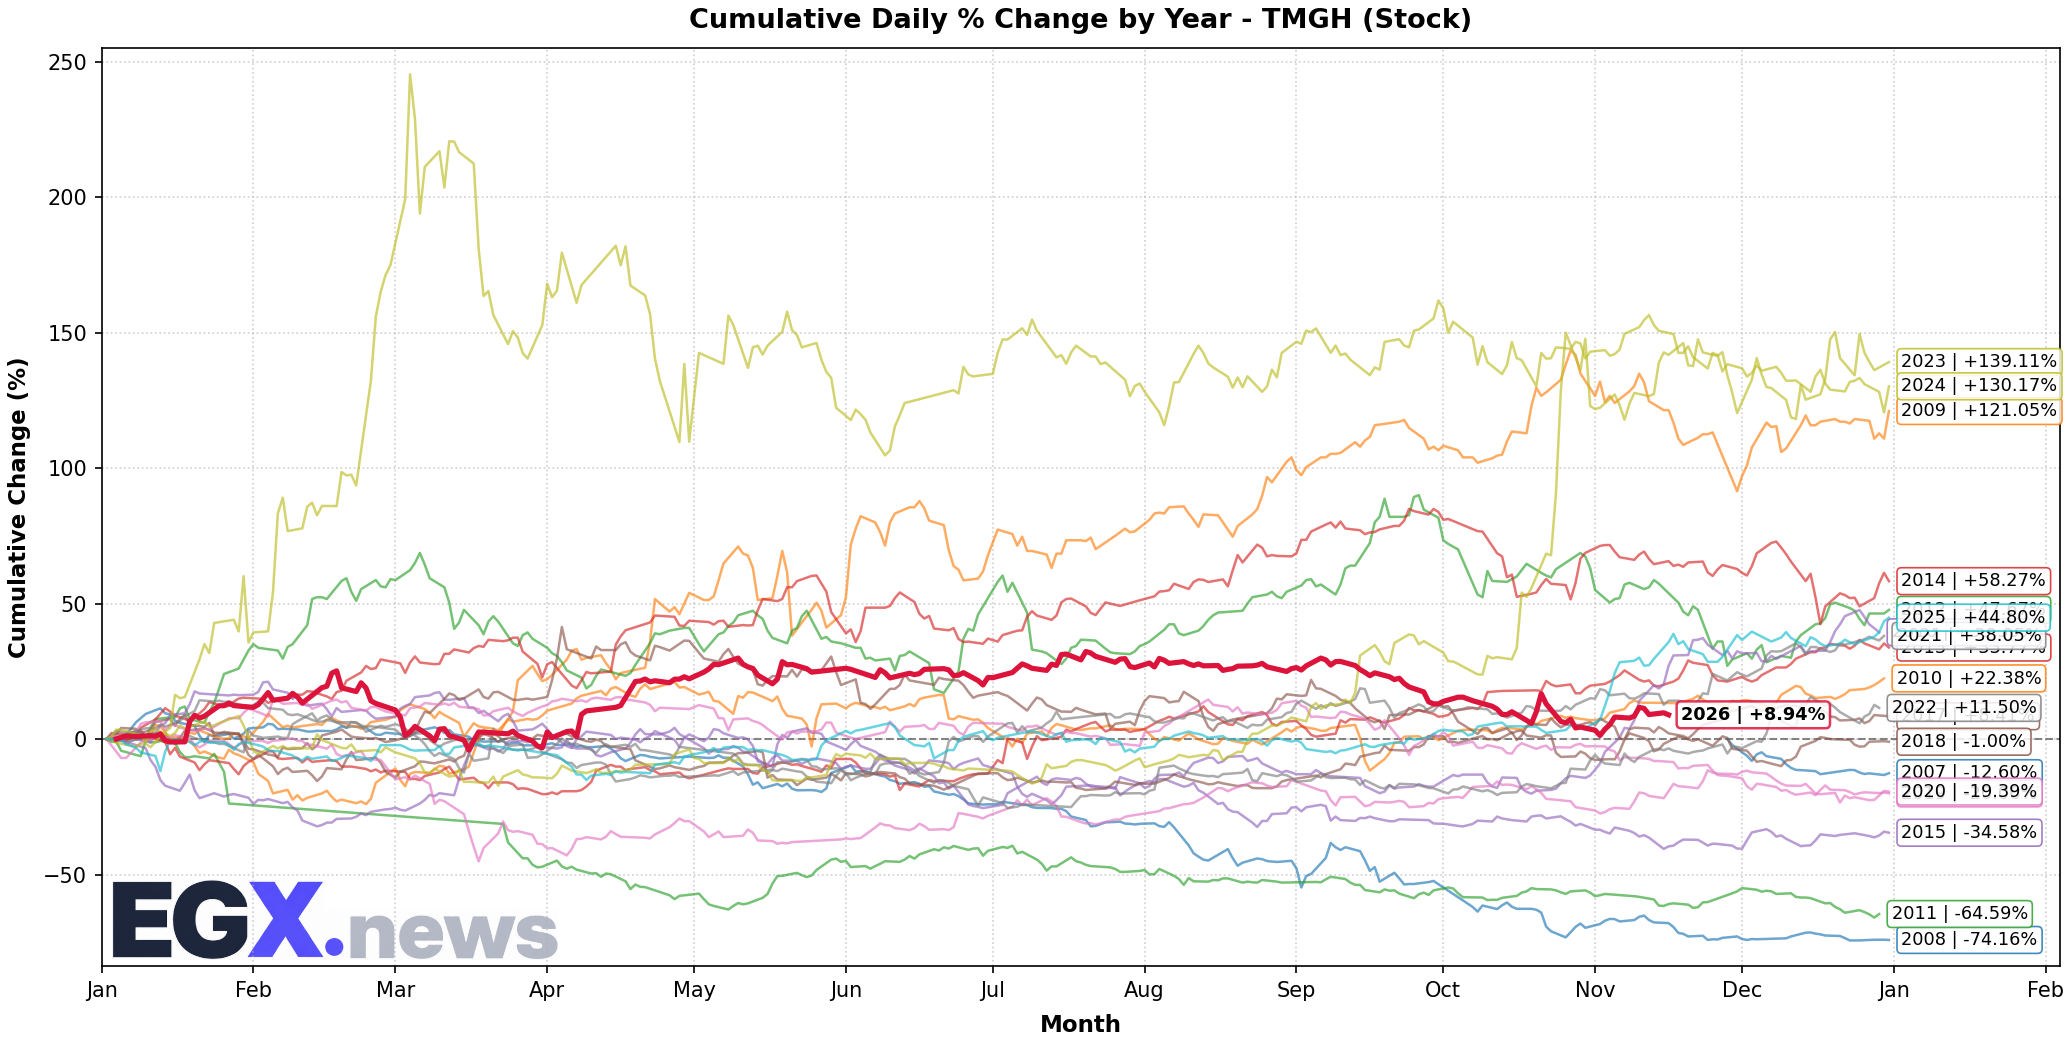
The stock slipped to EGP 28.90, a loss of 2.1%, due to weak demand for residential units and higher financing costs. The stock is trading below its 20‑day average of EGP 30.50, with a pivotal support at EGP 27.50 stemming from accumulated buying interest from value‑focused investment funds. Fundamentally, contract sales for the WEST project reached 5,500 units, of which 1,700 have already been delivered, reinforcing the outlook for future cash flows. However, downside pressure remains unless the market shows renewed appetite for buying on dips.
Abu Qir Fertilizers (ABUK)
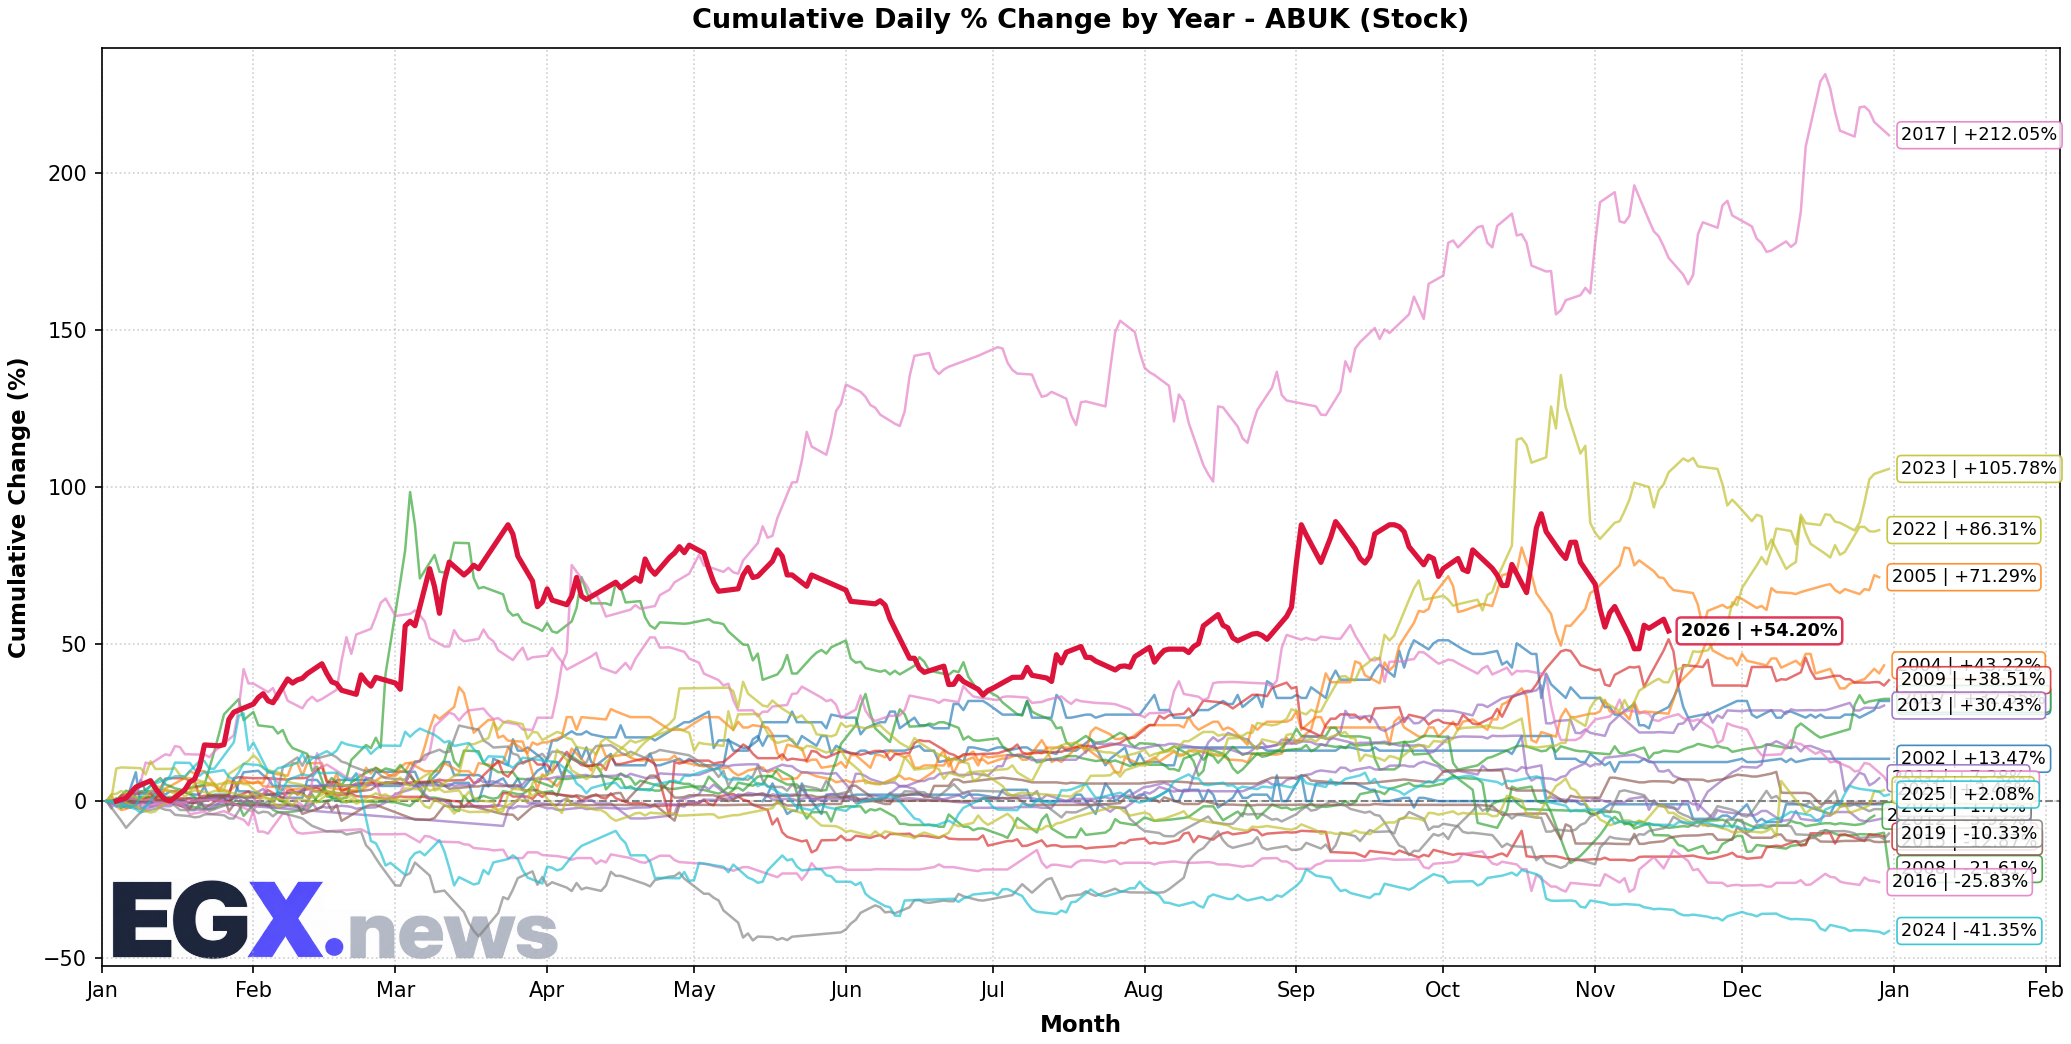
The stock closed at EGP 12.40 after a decline of 1.8%, driven by concerns over weakening global demand for nitrogen fertilizers and rising natural‑gas costs. The current price‑to‑earnings (P/E) ratio stands at 8.5, making the stock attractive from a valuation perspective if gas prices stabilize. The stock finds short‑term support at EGP 12.00, while resistance at EGP 13.20 represents a level to test buying strength.
Sewedy Electric (SWDY)
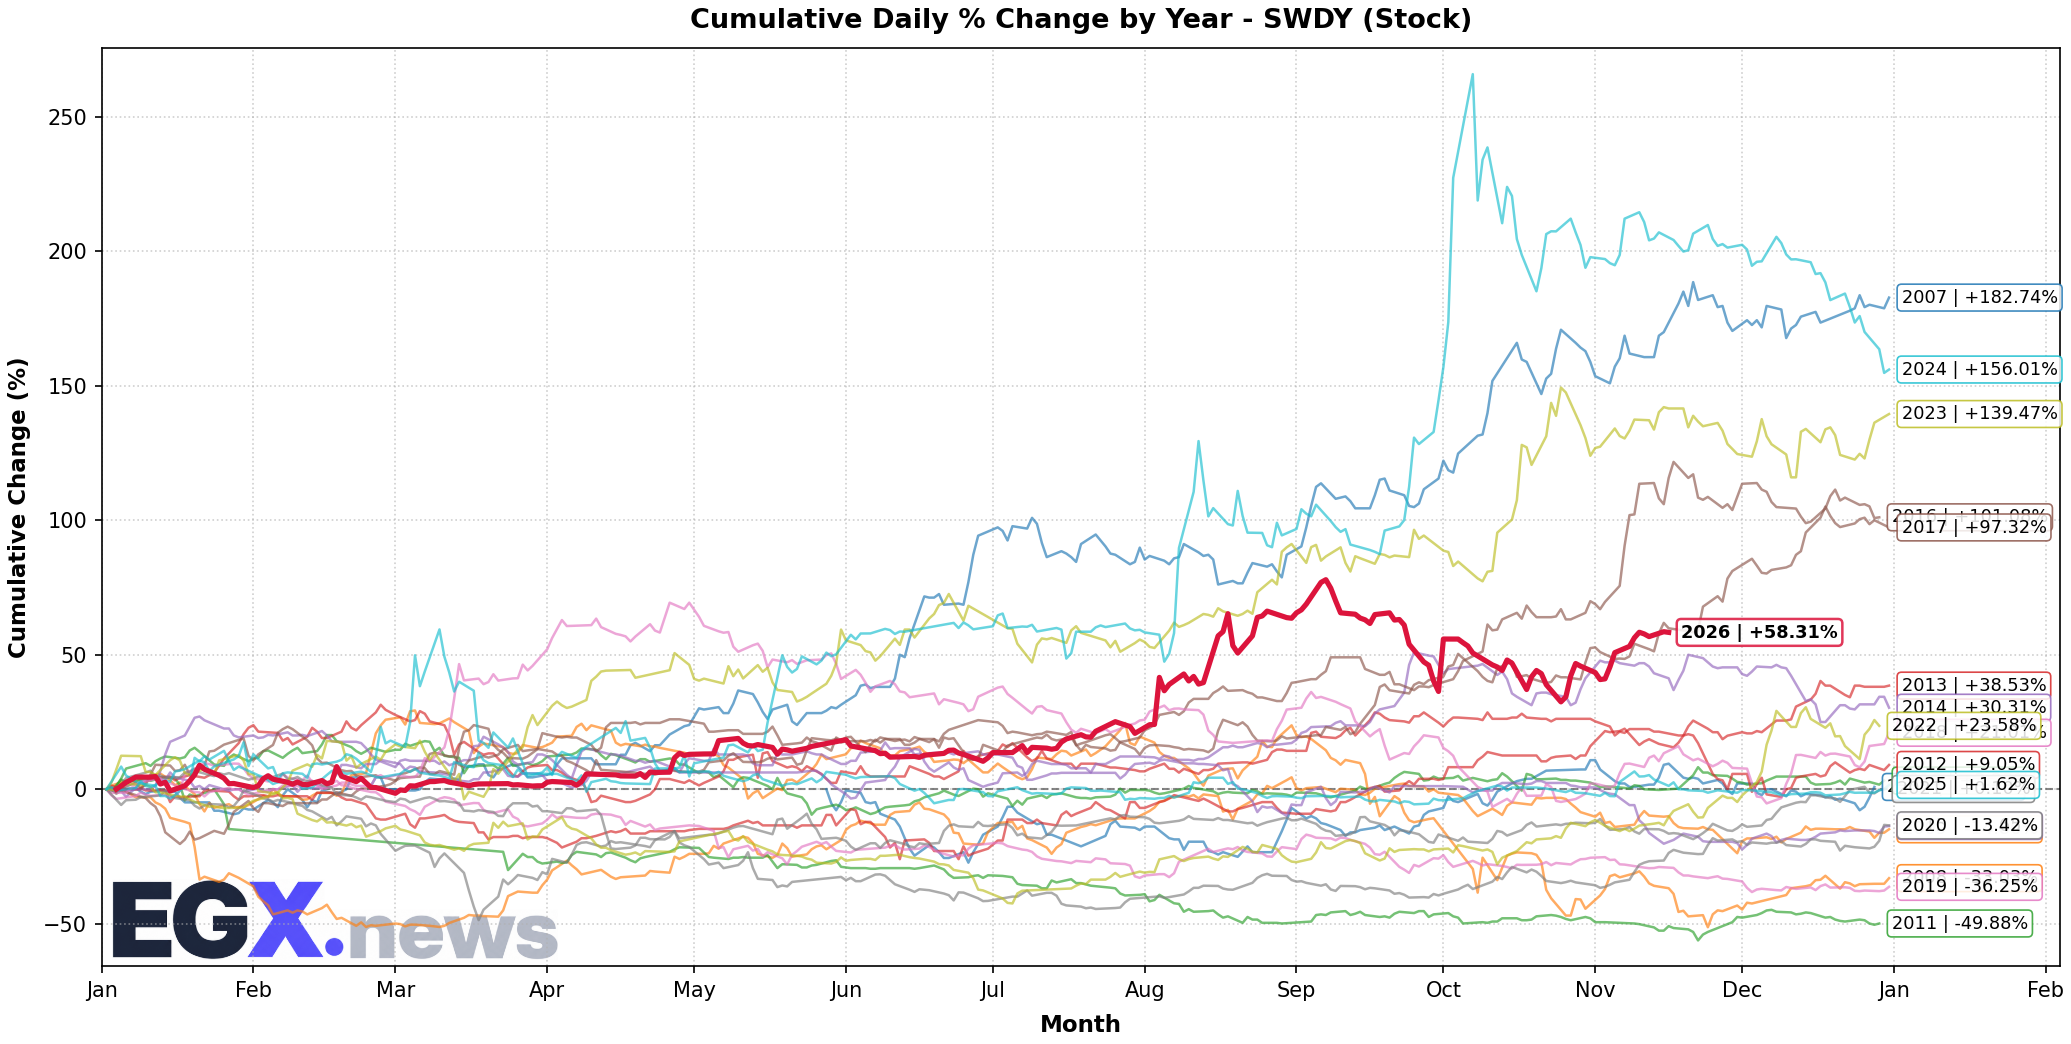
The stock fell to EGP 9.75, a loss of 2.5%, amid concerns over slowing execution of renewable‑energy projects and volatility in supply contracts. Technical analysis shows a mild ascending triangle with support at EGP 9.50 and resistance at EGP 10.20. Fundamentally, the net‑debt‑to‑EBITDA ratio is 2.3, indicating a moderate ability to bear financing burdens if ongoing project revenues improve.
Core Stocks Comparison
| Stock | Close (EGP) | Daily Change | P/E Approx | Near Support | Near Resistance |
|---|---|---|---|---|---|
| COMI | 63.20 | +0.4% | 5.8 | 62.00 | 65.00 |
| TMGH | 28.90 | -2.1% | 12.3 | 27.50 | 30.50 |
| ABUK | 12.40 | -1.8% | 8.5 | 12.00 | 13.20 |
| SWDY | 9.75 | -2.5% | 10.2 | 9.50 | 10.20 |
Macroeconomic Drivers and Policies
- Balance‑of‑payments surplus: The total surplus amounted to $2.8 billion in the past fiscal year, providing support for the exchange rate and easing pressure on foreign‑exchange reserves.
- Interest‑rate stability: The central bank indicated it could hold rates steady in the coming quarter to curb inflation without hindering credit activity.
- Inflation‑linked subsidies: The government is adjusting fuel and energy subsidies according to price indices, limiting the fiscal deficit and bolstering purchasing power.
- WEST project sales: Orascom Development announced sales contracts for 5,500 units, of which 1,700 have been delivered, boosting the company’s operating liquidity and sending positive signals to the real‑estate sector.
- Renewable‑energy tilt: A statement from the Ministry of Petroleum revealed talks with global firms to expand oil‑export capacity and stimulate investments in green‑hydrogen projects, which could create future demand for services and energy stocks.
Session Opening Outlook
Based on the preceding data, we expect the market to open with limited divergence:
- The EGX30 may test the 22,400‑22,500 point range with a slight upward bias if leading financial‑sector stocks absorb selling pressure.
- The EGX70 is likely to continue showing relative weakness below the 5,800‑point level, with a chance of an immediate rebound if buying interest emerges on dips, supported by positive news on real‑estate sales or inflation data coming in below expectations.
- At the individual‑stock level, COMI is likely to enjoy relative support owing to its strong fundamentals and the flow of liquidity toward the banking sector, while TMGH could remain under pressure unless clear signals appear to accelerate contract sales or improve financing terms from local banks.
- Export‑oriented stocks such as ABUK could benefit from any stabilization in global commodity prices, whereas SWDY may stay vulnerable to fluctuations tied to the execution of energy‑transition projects.
Expected Opening Levels
| Index/Stock | Expected Opening Level | Expected Intraday Volatility Range |
|---|---|---|
| EGX30 | 22,420‑22,480 | +/- 0.6 % |
| EGX70 | 5,780‑5,820 | +/- 0.8 % |
| COMI | 63.00‑63.40 EGP | +/- 0.5 % |
| TMGH | 28.60‑29.00 EGP | +/- 0.7 % |
| ABUK | 12.20‑12.60 EGP | +/- 0.6 % |
| SWDY | 9.60‑9.90 EGP | +/- 0.7 % |
Conclusion and Recommendations
The morning session mixes external pressures (U.S. dollar strength, geopolitical tensions) with domestic support (balance‑of‑payments surplus, inflation‑linked subsidy policies, progress in real‑estate sales). A selective approach is advised:
1. Focus on stocks with solid fundamentals such as COMI and the large banks, which benefit from incoming liquidity and stable dividend payouts.
2. Buy on dips in the mid‑cap real‑estate sector (TMGH) only if there is confirmation of renewed contract‑sale momentum or improved financing terms from local banks.
3. Monitor basic‑materials linked stocks (ABUK) for any sign of stabilizing natural‑gas prices or a rise in global fertilizer demand.
4. Exercise caution with highly financing‑sensitive stocks like SWDY, considering them only as a short‑term hedge if clear bullish technical signals appear, such as a decisive break above resistance.
In the end, caution remains the prevailing stance, with a tendency for selective buying on pullbacks that coincide with improvement in macro indicators or a flow of positive news on fiscal and monetary policy.
Live Egyptian Equities Coverage
Track real-time quotes, order book market depth, and quantitative technical analytics for all 299 listed companies.
Open Real-Time Market Terminal →